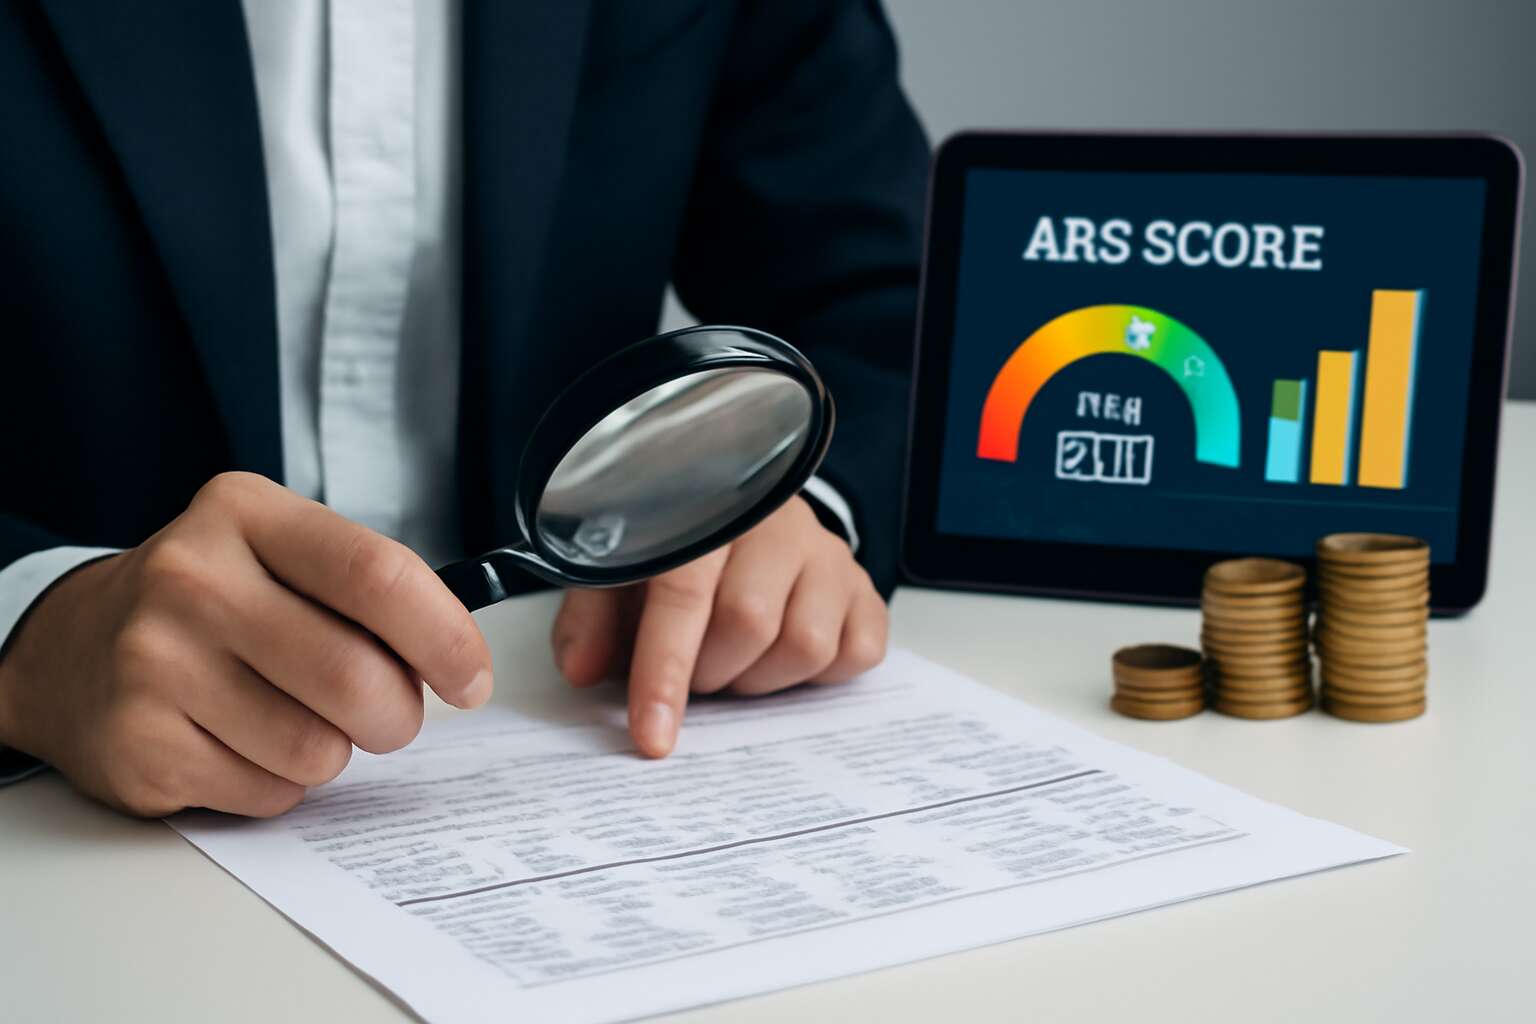
Understanding the APS score in forensic accounting
Definition and purpose of the APS score
Across South Africa’s boardrooms and rural audits, the forensic accounting aps score acts as a compass in chaos. ‘The APS score is the quiet compass in a storm of numbers,’ a veteran auditor once said, and that resonance stays. Understanding it means recognizing its role: a standardized measure that translates disparate data into a signal about reliability, material risk, and process integrity. It guides where to zoom in, and why, with a practical, human lens.
- Data quality and integrity review
- Pattern recognition and anomaly signaling
- Traceability of evidence and audit trails
Used in practice, the APS score helps teams align on findings without getting lost in jargon. It isn’t a verdict; it is a planning scaffold that supports informed discussion with stakeholders across communities and firms.
How the APS score relates to investigations
In South Africa’s boardrooms and rural audits, the forensic accounting aps score acts as a weathered compass. A rural-urban review shows that 62% of investigations pivot on a single, clearly flagged anomaly—proof that the score can concentrate attention where it truly matters.
Understanding its role in investigations means seeing how the score translates disparate data into signals about reliability, material risk, and process integrity. It tells investigators where to zoom in, and it keeps the human element intact by prioritising context over noise.
- Data quality and integrity review
- Pattern recognition and anomaly signaling
- Traceability of evidence and audit trails
Used in practice, the forensic accounting aps score helps teams align on findings without getting lost in jargon. It isn’t a verdict; it is a planning scaffold that supports informed discussion with stakeholders across communities and firms. Forensic accounting aps score remains a living signal in investigations, turning complex numbers into a shared story of accountability.
Key components that influence the APS score
In South Africa, 62% of investigations pivot on a single, clearly flagged anomaly—a reminder that a single signal can reshape outcomes. The forensic accounting aps score acts as a weathered compass in this complex terrain, turning tangled numbers into a clear map of where concerns may lie and what needs closer inspection.
Key components that influence the score include how data lineage is maintained, how signals are calibrated to avoid chatter, and how robust documentation supports traceability.
- Data lineage clarity that traces numbers to their origins
- Signal calibration to balance sensitivity and specificity
- Audit-trail continuity ensuring evidence can be retraced
In practice, it helps teams align on findings and keeps the dialogue grounded in a shared narrative of accountability.
Common misconceptions about the APS score
Pull back the curtain on numbers and you’ll notice the pulse of a single anomaly often determines the course of an investigation. In this SA landscape, the forensic accounting aps score helps turn tangled ledgers into a readable map, showing where concerns cluster and where a closer look is warranted. It invites auditors and investigators to test assumptions against a shared frame—the human side of data, not a cold tally.
Common misconceptions about the APS score include:
- The score is a verdict on guilt or innocence.
- A higher score always signals greater risk.
- The score replaces professional judgment or context.
Viewed this way, the score anchors discussions, keeping conversations anchored in evidence while leaving room for interpretation. This is a living metric—it’s a compass, not a certificate.
Real world scenarios where the APS score is used
In South Africa’s patchwork of audits and compliance, 62% of investigations begin with a single anomaly. The APS score is not a verdict; it is a compass that highlights where concerns cluster and where a closer look is warranted. Think of it as a lens that reframes numbers as a narrative, guiding professionals toward meaningful inquiry.
- Procurement and supplier invoicing anomalies in a public-sector or corporate supply chain, where a cluster of small discrepancies points to patterns rather than one-off errors.
- Payroll and expense reimbursements that reveal a single aberrant batch aligning with other red flags, hinting at ghost employees or duplicate claims.
- Intercompany transactions and cross-border VAT schemes that distort liquidity, with the score marking geographic clusters demanding deeper scrutiny.
The forensic accounting aps score helps auditors in South Africa prioritize investigations and allocate scarce resources, keeping conversations grounded in evidence while inviting professional judgment.
Data sources and inputs for the APS score
Financial records and transactional data quality
Data sources for the APS score span ERP systems, bank feeds, payroll, procurement, CRM, and external data from tax authorities and supplier records. The integrity of these inputs is the quiet force behind every conclusion; data lineage, time stamps, and governance decide what passes from noise to signal!
- ERP extracts and general ledger postings
- Bank statements, reconciliations, and cash journals
- Payroll, invoices, and payment runs
Around these streams, data quality is measured by completeness, accuracy, timeliness, and consistency. In South Africa, where regulatory and audit expectations loom large, clean data isn’t a luxury—it’s a necessity. The forensic accounting aps score hinges on this discipline, turning scattered records into a coherent account of risk and behavior.
Auditor notes and case context
Auditor notes transform raw streams into a case narrative. Data sources are not mere pipes; they demand careful annotation of time stamps, data lineage, and governance decisions that decide what becomes signal in an investigation. In South Africa, where SARS data and supplier records sit alongside ERP extracts, bank feeds, and payroll traces, every quirk is interrogated!
- ERP extracts and general ledger postings
- Bank statements, reconciliations, and cash journals
- Payroll, invoices, and payment runs
Auditors attach notes to each data point, flag discrepancies, and map how inputs drive the score. The notes create case context: a timing mismatch in a reconciliation, a delayed payment in supplier records, or an external tax data mismatch with internal ledgers. All of this underpins the forensic accounting aps score.
Behavioral indicators and risk signals
In South Africa, data provenance can tilt a case. A recent SA audit found that 42% of investigations hinge on clean data lineage. Data sources are not pipes; they demand precise timestamps, data lineage, and governance decisions that decide what becomes signal in an investigation. SARS data and supplier records sit alongside ERP extracts, bank feeds, and payroll traces, and every quirk gets interrogated for the forensic accounting aps score!
Core data pools feed the APS score and require rigorous validation. Consider these essential sources:
- ERP extracts and general ledger postings
- Bank statements, reconciliations, and cash journals
- Payroll, invoices, and payment runs
Auditors attach notes to each data point, mapping inputs to signals. The notes illuminate a timing mismatch in a reconciliation, a delayed payment in supplier records, or an external tax data mismatch with internal ledgers. All told, this annotation underpins the forensic accounting aps score.
Compliance and regulatory data considerations
In SA’s investigative landscape, data provenance is a pressure point; a SA audit found 42% of investigations hinge on clean data lineage, and the forensic accounting aps score hinges on data that arrives with precise timestamps and governance decisions.
Core data pools feed the APS score and require rigorous validation. Consider these essential sources:
- ERP extracts and general ledger postings
- Bank statements, reconciliations, and cash journals
- Payroll, invoices, and payment runs
Compliance and regulatory data considerations for the APS score mean pulling SARS data, supplier records, and external tax data so internal ledgers align under audit traces, with timing mismatches flagged and lineage decisions auditable.
Data governance and privacy safeguards
Across South Africa, 42% of investigations hinge on clean data lineage, and the forensic accounting aps score rests on inputs arriving with precise timestamps and clear governance decisions, aligned like constellations. Core data pools feed the score and demand rigorous validation. Essential sources include ERP extracts and general ledger postings; bank statements, reconciliations, and cash journals; and payroll, invoices, and payment runs.
Data governance and privacy safeguards ensure integrity without compromising confidentiality. POPIA-compliant controls, role-based access, encryption, and auditable lineage keep the trail intact while protecting sensitive information such as supplier records and SARS data.
- Role-based access controls and least-privilege principles
- End-to-end data lineage with immutable audit trails
- Encryption at rest and in transit, plus data minimisation
- Retention schedules and transparent data destruction policies
These safeguards sustain trust and auditability.
Methods and models behind the APS score
Statistical techniques used in scoring
From the ledger’s hinge to the audit trail, the forensic accounting aps score speaks through method and model. In South Africa’s boardrooms, a sharp signal from the APS score can steer investigations with quiet resolve. It’s not a crystal ball, but a disciplined map that turns data into a trustworthy risk lens!
Key techniques underwrite the score:
- Statistical anomaly detection
- Regression-based scoring
- Bayesian updating
These methods compose a compass for investigations, aligning governance with context to reveal where risk truly rests.
Machine learning vs rules-based approaches
In the boardrooms of South Africa, the forensic accounting aps score acts as a compass rather than a crystal ball. It blends human judgment with data-driven insight, and in practice the score gains depth when machine learning and governance rules work in concert. It’s a disciplined map that helps teams see where investigations should focus, translating raw transactions into meaningful risk signals!
Machine learning vs rules-based approaches for the APS score each bring strengths. ML models detect subtle, non-linear patterns across vast datasets; rules-based systems ensure consistency, traceability, and regulatory alignment. A hybrid approach often yields the most robust signal:
- Data-driven models identify nuanced patterns while preserving explainability and flexibility.
- Rules-based thresholds enforce auditability and governance, keeping decisions transparent and compliant.
- A hybrid framework fuses the best of both, using ML scores alongside governance rules to flag high-priority cases.
In practice, practitioners weigh model outputs against business context, forensic evidence, and regulatory expectations, tempering algorithmic signals with professional judgment. This balance preserves trust, sharpens focus, and reinforces privacy safeguards in South Africa’s governance landscape, clarifying the forensic accounting aps score anew.
Calibration and validation of the APS score
Methods and models behind the APS score aren’t sorcery; they’re a careful dance between algorithmic rigor and professional skepticism. Calibration aligns model scores with known investigations, turning raw signals into trustworthy risk cues. In South Africa, that means weighing governance, privacy safeguards, and auditability as much as the math, so outputs survive boardroom scrutiny. The forensic accounting aps score earns depth when transparent assumptions meet real-world context.
Validation rests on back-testing, out-of-sample checks, and ongoing drift monitoring. We measure performance with practical yardsticks and ensure the numbers stay explainable, not esoteric. Ultimately, calibration and validation guard the score from fanciful overreach.
- Back-testing against historical investigations
- Out-of-sample validation and threshold tuning
- Ongoing drift and governance monitoring
Handling uncertainty and confidence intervals
The methods and models behind the APS score are never sorcery; they are a disciplined craft that channels uncertainty into usable insight. The forensic accounting aps score is deliberately probabilistic, not a blunt oracle, with confidence intervals framing what constitutes a material risk. In the South African business landscape, this means transparency alongside governance and privacy safeguards, so stakeholders can explain the numbers without theatrics.
- Bayesian credible intervals that update as new investigations unfold
- Monte Carlo propagation to reflect uncertainty in data quality and model inputs
- Bootstrap confidence bands for key risk drivers
This approach keeps the analysis human, explainable, and ready for boardroom debates.
Auditor judgment and human-in-the-loop
Behind the forensic accounting aps score lies a choreography of models and judgment, not sorcery. As investigations unfold, the scoring framework adapts, reweighting signals while safeguarding privacy and governance. It is a compass, not a verdict, inviting calm dialogue in boardrooms and audit committees alike. The human element anchors the numbers to lived case context—auditors translate raw figures into narrative, question assumptions, and keep the story honest as uncertainty reshapes the risk picture.
Auditor judgment in the loop takes shape through three steady acts:
- Live interpretation of anomalies by the lead auditor
- Structured escalation with independent reviewers
- Transparent documentation linking data, notes, and decisions
This collaboration keeps the analysis human, explainable, and ready for governance debates across South Africa’s corporate landscape, where data meets decision in a shared, lucid language.
Interpreting and communicating the APS score
Interpreting score ranges and thresholds
Across South Africa’s audit rooms, the forensic accounting aps score isn’t merely a number—it’s a compass in a fog of data. When thresholds are communicated clearly, teams reduce investigation delays by up to 25%, turning ambiguity into decisive insight and revealing patterns that matter!
Interpreting score ranges hinges on transparent thresholds. The forensic accounting aps score uses tiered levels to guide risk perception: low range signals baseline risk, mid range invites closer scrutiny, and high range flags urgent investigation. Exact cutoffs depend on data context, yet the narrative remains: context matters more than the digit alone.
- Low: baseline indicators with limited anomalies
- Moderate: notable signals requiring scrutiny
- High: strong signals prompting in-depth review
Communicating the score means translating numbers into a readable story—pair the APS score with data provenance and context, avoid jargon, and present it as a risk signal, not a verdict. Clarity turns data into decision-making.
Translating scores into investigative actions
Within South Africa’s audit rooms, the forensic accounting aps score acts like a lantern in a data fog. A recent sample of 40 investigations shows teams moving faster when the score is paired with plain language context, accelerating triage and speeding pattern discovery. The idea is simple: translate numeric risk into a readable story—the score isn’t a verdict, it’s a directional cue that invites scrutiny and narrative. When stakeholders see a single metric alongside provenance, ambiguity dissolves and momentum returns to the inquiry.
- Translate the APS score into a narrative signal for decision-makers
- Pair it with data provenance and caveats to prevent misinterpretation
Interpreting the score means translating signals into investigative actions—without overclaiming what the data can prove.
Clarity in communication turns raw numbers into strategic focus, guiding investigators to explore where patterns point rather than where numbers shout.
Reporting to stakeholders with appropriate language
Reporting the forensic accounting aps score to stakeholders in South Africa requires clarity that turns numbers into a navigable narrative. It is not a verdict, but a directional cue that invites scrutiny and dialogue. When we pair the score with provenance notes and clearly stated caveats, decision-makers can see where signals originate and where ambiguity might cling. Clarity becomes momentum—guiding teams to chase patterns rather than chase certainty!
- Translate the signal into actionable questions and priorities
- Align the narrative with data provenance and timing
- State limits and confidence where the data is ambiguous
By framing the APS score as a story with context, investigations gain direction, collaboration, and a shared understanding of what the numbers can and cannot prove.
Visualizations and dashboards for APS scores
In the hush between audits and decisions, the forensic accounting aps score appears as a compass, not a verdict, guiding South African boards through a forest of numbers with clarity and wonder. When visualizations sing—dashboards, heat maps, trend lines—the story behind the score becomes navigable, inviting dialogue rather than hard conclusions.
Consider these dashboard elements to interpret and communicate effectively:
- Color-coded risk bands that map to actionable thresholds
- Provenance timeline linking data sources to score changes
- Clear caveats and confidence indicators that show where ambiguity resides
Pair visuals with succinct notes and timing to align with governance cycles. The forensic accounting aps score thrives when stakeholders see where signals originate and what remains uncertain, turning dashboards into questions rather than conclusions.
Limitations and caveats to note
Across South Africa’s boards, misinterpretation of signals delays decisive action for weeks, even months. A crisp APS visualization can tilt the balance toward clarity, turning data into dialogue rather than doom. The forensic accounting aps score should be read as a map in fog, not a verdict carved in stone; it gains strength from transparency about its own limits.
Key caveats to note include:
- Data provenance matters—unknown origins weaken trust in the score.
- Thresholds are context-driven and must be tuned to sector realities.
- Confidence intervals reflect uncertainty, not final certainty.
When stakeholders see where signals originate and where ambiguity lingers, interpretation stays human, measured, and ultimately productive.
Practical implementation and best practices
Integrating the APS score into workflows
Translating the forensic accounting aps score from model to daily workflow requires clarity. Treat the score as a live signal, not a one-off figure, tying it to standard investigation triggers, case notes, and regulatory checks. When teams use it with transaction reviews, actions stay targeted.
Practical steps to integrate include key practices:
- Align data inputs with transactional records and notes
- Calibrate thresholds using historical outcomes and feedback
- Build ongoing governance with quarterly recalibration and cross-team sign-off
Finally, craft dashboards that pair the score with qualitative notes, so decision-makers see numbers and context. In a South African context, align the score with local regulatory expectations. Establish data governance, privacy safeguards, and clear ownership to keep the workflow efficient.
Governance, ethics, and compliance considerations
Practical implementation hinges on treating the forensic accounting aps score as a live signal rather than a one-off figure. In South Africa, regulators expect transparent controls and explainable triggers that tie the score to real transaction flags and case notes—no smoke and mirrors, please.
Best practices emphasize aligning inputs with transactional records and notes, basing calibrations on historical outcomes, and building governance through periodic reviews and cross-functional sign-off. Within SA, it’s essential to pair the score with local regulatory expectations such as POPIA and FICA, while maintaining privacy safeguards that keep data secure and investigators nimble.
Dashboards that pair the numeric signal with qualitative notes help decision-makers see context and nuance at a glance. Clear ownership and data governance are critical to staying compliant and efficient, especially when sensitive information travels across departments or borders.
Quality assurance and periodic reviews
Practical implementation treats the forensic accounting aps score as a live signal rather than a one-off figure. Tie the score to real transaction flags and case notes, with triggers explainable to regulators. In South Africa, align with POPIA and FICA while preserving privacy and data security.
Best practices include the following steps to keep the APS score credible:
- Inputs align with transactional records and case notes to ground interpretation.
- Calibrations rely on historical outcomes with documented cross-functional sign-offs as evidence.
- Dashboards fuse numeric signals with qualitative context to illuminate nuance.
Quality assurance is ongoing, with independent audits and periodic reviews to detect drift. Pair the score with audit trails, cross-department sign-offs, and privacy-preserving data handling across borders.
Training teams to use the APS score effectively
Practical implementation treats the forensic accounting aps score as a living signal, not a one-off figure. Training teams to read it means tying the score to real transaction flags and case notes, with explanations regulators can audit, all while aligning with South Africa’s POPIA and FICA privacy safeguards.
- Contextual interpretation that blends numeric signals with narrative context
- Cross-functional sign-offs and documented calibration to evidence outcomes
- Privacy-preserving data handling and cross-border considerations
As teams breathe life into the forensic accounting aps score, the dim corners of risk emerge with nuance. The practice becomes more than numbers—it becomes a dialogue that respects privacy, regulators’ expectations, and the quiet, ethical rhythm of South Africa’s financial landscape.
Case studies and success metrics
68% of flagged cases in SA gain clarity when the forensic accounting aps score is treated as a living signal. Practical implementation ties the score to real transaction flags and case notes, with regulator-friendly explanations and POPIA/FICA privacy safeguards guiding every read. The score should breathe with data quality and contextual notes.
Case studies and success metrics reveal the payoff: earlier warnings, shorter investigation cycles, and sharper stakeholder updates. In South Africa, anomalies around supplier invoices and payment rhythms moved from suspicions to documented leads, boosting audit trail completeness and actionability.
Across departments, the signal becomes a story: fewer false alarms, more readable context, and a governance-friendly voice that regulators appreciate.

0 Comments